Kenya’s latest major share transaction has reignited a national debate over privatisation, public funds and whether ordinary citizens are benefiting from the sale of state-owned assets.
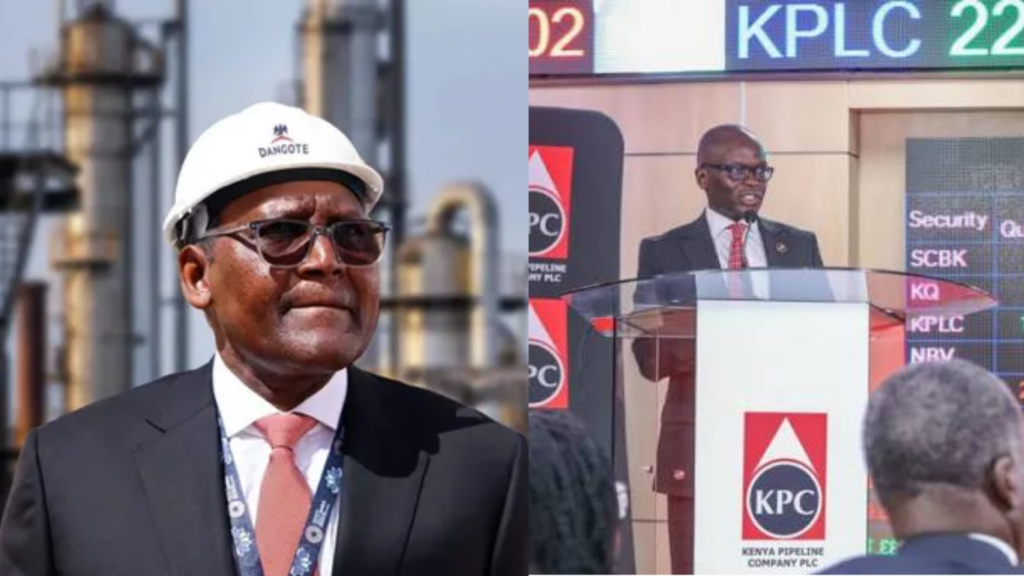
Is Kenya for sale, or is the government opening the door to private investment in strategic national companies? That is the question emerging after Nigerian billionaire Aliko Dangote acquired a 24.76% stake in the Kenya Pipeline Company (KPC) in a transaction valued at approximately KSh42.5 billion.
The deal has placed the government’s privatisation programme under renewed scrutiny, with questions being raised about the role of public institutions, the participation of ordinary Kenyan investors and the transparency of major transactions involving national assets.
Dangote acquires a major stake in KPC
Reports published on October 21, 2026, indicated that Dangote had acquired approximately 4.5 billion KPC shares at KSh9.02 per share, giving him a 24.76% stake in the company.
The shares were reportedly sold by state-backed institutions, raising questions about why these institutions were disposing of significant holdings less than eight months after KPC was listed on the Nairobi Securities Exchange.
KPC plays a strategic role in Kenya’s petroleum supply chain, transporting fuel through its pipeline network to various parts of the country and the wider region. Any major change in its ownership therefore attracts public interest.
The transaction has also drawn attention because it involves a strategic national company whose operations are closely linked to Kenya’s energy security and economic activity.
Are ordinary Kenyans being left behind?
One of the central questions surrounding the transaction is whether ordinary Kenyans had a fair opportunity to benefit from the sale of public assets.
During the KPC initial public offering, local retail investors reportedly bought shares worth approximately KSh4.1 billion against an allocation of KSh21.2 billion. The figures point to relatively low participation by individual investors compared with the amount allocated to them.
The subsequent sale of a large block of shares to a single major investor has renewed debate over whether Kenya’s privatisation programme is sufficiently inclusive.
However, claims that ordinary investors are currently being deliberately locked out of trading KPC shares have not been independently established. Difficulties accessing a trading platform, market liquidity and restrictions on particular transactions are separate issues that require verification.
Ndindi Nyoro raises questions over public funds
Kiharu MP Ndindi Nyoro has raised concerns about the role of state-backed institutions in the KPC share transaction.
Nyoro has alleged that public institutions were pressured to purchase shares during the IPO before a substantial stake was sold to a private investor. He has also called for greater disclosure concerning the ownership and financing arrangements surrounding proposed energy investments linked to Dangote.
These remain allegations and require documentary evidence and responses from the institutions involved. They should not be treated as proof of wrongdoing by the government or the investor.
Nevertheless, the questions about the management of public funds are significant. When pension funds and other public institutions invest in or dispose of major shareholdings, Kenyans have a legitimate interest in understanding the commercial rationale, risks and expected returns.
What does the deal mean for President Ruto’s privatisation agenda?
President William Ruto’s administration has pursued privatisation and the mobilisation of private capital as part of its wider economic agenda.
Supporters of privatisation argue that private investors can bring capital, commercial expertise and opportunities for expansion. Foreign investment can also strengthen business relationships and support economic growth.
Critics, however, question whether the sale of stakes in strategic companies delivers sufficient benefits to ordinary citizens, particularly when public institutions are involved.
The Dangote transaction has brought those competing arguments into focus. The key issue is not simply the nationality or wealth of the buyer, but whether the transaction was conducted transparently, complied with the law and protected the interests of the public.
The reported share sale does not, by itself, establish that President Ruto improperly favoured Dangote or that the country’s assets are being sold unlawfully.
The questions Kenyans deserve answered
As debate over the transaction continues, several issues warrant clear answers from the relevant institutions:
- Why did the state-backed institutions decide to sell their KPC shares less than eight months after the IPO?
- What investment objectives and financial considerations informed the sale?
- Were the shares sold through a transparent and competitive process?
- What returns did the selling institutions realise, and how will those proceeds be used?
- What safeguards protect Kenya’s energy infrastructure and the interests of consumers?
- What measures will ensure ordinary Kenyan investors can participate meaningfully in future privatisations?
Clear answers, supported by published agreements, transaction disclosures and independent regulatory oversight, would help establish whether the transaction served the public interest.
Is Kenya for sale?
The acquisition of a major stake in KPC by a private investor is not, on its own, evidence that Kenya is being sold off. Privatisation can be a legitimate economic policy when it follows the law, protects public interests and delivers demonstrable value.
But the questions surrounding the KPC transaction cannot simply be dismissed. Public institutions, pension funds and strategic infrastructure carry responsibilities that extend beyond the interests of individual shareholders.
For Kenyans, the central concern is whether the country’s economic decisions are creating opportunities for citizens or concentrating ownership and influence in the hands of a few powerful investors.
The question is not whether Kenya should accept investment. It is whether every major sale of public assets can withstand public scrutiny—and whether Kenyans can see clearly who benefits, who bears the risk and what the country gains.